My customers have rights

My customers are not the Gambling Commission’s property

By Geoffrey Banks | 22 October 2026

I’ve been a bookmaker for decades despite not being that old. I’ve taken bets from people I’ve known for most of my working life. Some are wealthy, some aren’t. Some bet hundreds, others thousands. Most understand perfectly well what they’re doing. Gambling involves risk.

They’re my customers. Not the Gambling Commission’s.

They are adults spending their own money on a lawful pastime. They expect me to offer competitive odds, honour their bets, pay their winnings and treat them with honour.

They don’t expect to explain their salaries, savings, pensions or personal wealth to a stranger simply because they enjoy gambling. Or share it with my staff, quite understandably

And they certainly don’t expect a regulator to decide, years afterwards, whether I should have allowed them to bet.

Yet that is increasingly what the Gambling Commission’s enforcement department is doing.

The latest example is L&L Europe, which has agreed a substantial regulatory settlement following a Commission investigation. https://www.gamblingcommission.gov.uk/public-register/public-statement/detail/l-and-l-europe-limited-public-statement

There were genuine failings. Delayed withdrawals, inadequate responses to repeated failed deposits and breaches of agreed customer limits are matters a regulator should address.

But among the findings was criticism that L&L had not adequately established whether customer expenditure was proportionate to income or wealth.

There it is – affordability checks!
And although Andrew Rhodes has left the Gambling Commission to balls it up at Harris Hagen, the policies developed under his leadership have not simply disappeared with him. They’re doubling down on insane

Sarah Gardner is now Acting Chief Executive. The Commission remains responsible for explaining why its enforcement decisions demand financial assessments that its published policy says it doesn’t require.

Customers don’t want financial interrogation to have a bet.

The Commission talks endlessly about protecting customers. It might consider listening to them before they all end up at Stake. Com

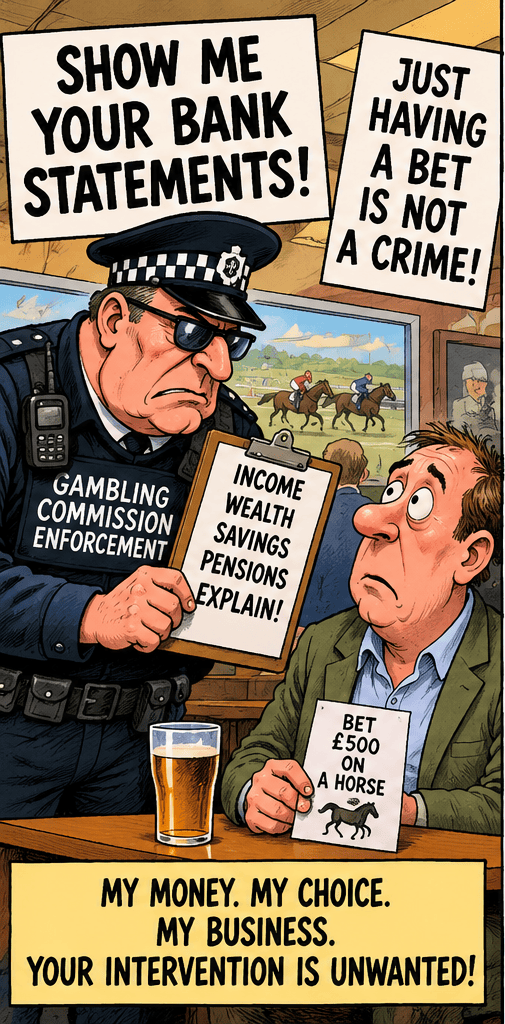
Many customers have made their objections to intrusive financial checks perfectly clear. They don’t want to hand over bank statements, payslips or access to their financial transactions to justify having a bet.

The Commission itself acknowledges that document checks are unpopular. Its financial risk assessment proposals are specifically intended to reduce reliance on them.

So why does its enforcement activity continue to encourage operators to investigate customers’ income and wealth?

I know customers who would sooner close an account than disclose their personal finances. I don’t blame them.

When did a bookmaker become entitled to examine someone’s bank statements simply because they want £500 on a horse?

And why should a successful businessman, who has spent decades accumulating his own wealth, have to prove to a gambling company that he’s allowed to enjoy it?

We don’t demand financial assessments before someone buys an expensive holiday, a luxury car or a painting.

Gambling carries risks, and those risks justify appropriate regulation. They do not justify treating every customer who spends substantial sums as financially incompetent.

The Commission increasingly forgets the difference.
Where is the evidence that these interventions work?

Here is the question Parliament should be asking.

Where is the convincing evidence that the financial interventions being imposed on customers actually reduce problem gambling?

Not evidence that some gamblers experience financial difficulties. We know that.

Not evidence that a credit-reference agency can identify missed payments or defaults. That is what credit-reference agencies do.

I mean evidence that requiring operators to interrupt betting, demand documents, investigate wealth and restrict customers produces a measurable reduction in gambling harm.

The Commission’s financial risk assessment pilot examined whether financial vulnerability could be identified and whether assessments could be conducted with minimal disruption.

That is not proof that the resulting interventions prevent problem gambling.

The Commission has decided to introduce financial risk assessments in stages and says it will continue evaluating their impact.

Yet operators are already being criticised through enforcement for failing to undertake financial enquiries that resemble the affordability assessments the Commission says it doesn’t require.

The burden should be on the regulator to demonstrate that its interventions are necessary, effective and proportionate. To prove these overbearing imposition on people are worthwhile

Instead, bookmakers face the financial consequences of failing to intervene, while the benefits of those interventions remain insufficiently demonstrated.

That is a remarkably one-sided arrangement.

Apparently, winning is now suspicious

Consider the recent Rank settlement involving Grosvenor Casinos.

The Commission criticised the absence of safer gambling interactions with a long-standing, wealthy customer who lost a substantial amount.

In another example, an established customer won around £260,000, subsequently lost £250,000 over 12 days and remained £10,000 ahead.

The Commission nevertheless criticised the absence of recorded safer gambling interactions.

A customer wins £10,000 and the regulator finds fault with the operator.

A pattern of substantial gambling is not, by itself, proof that the customer has a gambling problem. Nor does a wealthy customer become financially vulnerable merely because the regulator considers the sums involved large.

What troubles me is the disappearance of proportion and context.

I know customers for whom a £5,000 bet is entirely ordinary. I know others for whom £100 is significant.

That is why personal knowledge and commercial judgment matter.

But the Commission’s approach encourages operators to disregard that knowledge and intervene defensively, because an ex copper in the enforcement department may take a different view two years later.

If a bookmaker intervenes unnecessarily, the customer suffers the inconvenience. If the bookmaker doesn’t intervene, the Commission may impose a substantial settlement.

The regulator faces neither consequence.

A policy the enforcement department appears to ignore

In May 2025 the Commission explicitly stated that it had no regulatory requirements for affordability checks and wasn’t proposing any.

Andrew Rhodes had previously explained to Parliament that affordability policy was being addressed through the Government’s Gambling Act Review White Paper process.

He has since departed. But his departure doesn’t repeal the Commission’s published policy.

Indeed, senior Commission officials subsequently made clear that the organisation intended to continue the regulatory approach established during his tenure.

Sarah Gardner therefore inherits a question that Rhodes never satisfactorily resolved.

The Commission distinguishes financial risk assessments from traditional affordability checks, saying they identify serious financial difficulties rather than calculate what a customer can afford.

Yet in the L&L case, enforcement criticised failures to assess whether expenditure was proportionate to wealth or income.

One customer deposited £4,400 within eight hours. The Commission questioned the provenance of the money, including the absence of evidence that it originated from employment, business income or savings.

Other warning signs justified AML enquiries. But money won from another bookmaker isn’t inherently suspicious, and customers aren’t obliged to finance their gambling from wages.

Checking whether funds are legitimate is one thing. Assessing whether a customer is sufficiently wealthy to gamble is another.

If the Commission’s policy says affordability checks aren’t required, why does its enforcement department appear to be demanding financial judgments that serve much the same purpose?

Sarah Gardner should explain whether enforcement is applying the Commission’s policy or developing its own.
When did an operator’s own policy become law?

L&L’s internal procedures said customer funds should ideally be evidenced as coming from employment or business income.

The Commission criticised the company for not following those procedures.

The LCCP requires effective AML controls, including proper implementation of relevant policies. But an operator’s voluntary precaution doesn’t automatically become an additional licence condition.

If a bookmaker introduces safeguards beyond the regulatory minimum, should it face greater punishment merely because it hasn’t followed every detail of them?

That creates a perverse incentive.

Write an ambitious compliance manual and hand the Commission more ammunition. Write the bare minimum and give it fewer opportunities to find fault.

The regulator should be encouraging operators to improve their procedures, not using voluntary commitments as an excuse to enlarge their regulatory obligations.If so, what should John Pierce and his merry band of stormtroopers in the enforcement unit fine themselves for departure from aim to permit, for example? Or application of affordability based enforcement? That’s a material breach. How many millions Mr Pierce should you pay?

If failures against those voluntary standards are increasing financial settlements, the Commission should explain how those penalties are calculated.

An operator shouldn’t be punished twice for the same underlying deficiency because it also happens to appear in its own manual.

The operators have helped create this mess

The industry cannot escape criticism either.

Major bookmakers began conducting their own affordability checks, often introducing restrictions and demands for financial information that went beyond what the Commission had expressly required. Unquestionably this was, in part l, driven by a desire to profile all clients and filter out traders

Instead of challenging the regulatory direction, parts of the industry effectively implemented it themselves.

Customers paid the price in intrusive questions, delayed transactions and closed accounts. They’ve departed gambling or opened up in Curaçao

Then came the settlements.

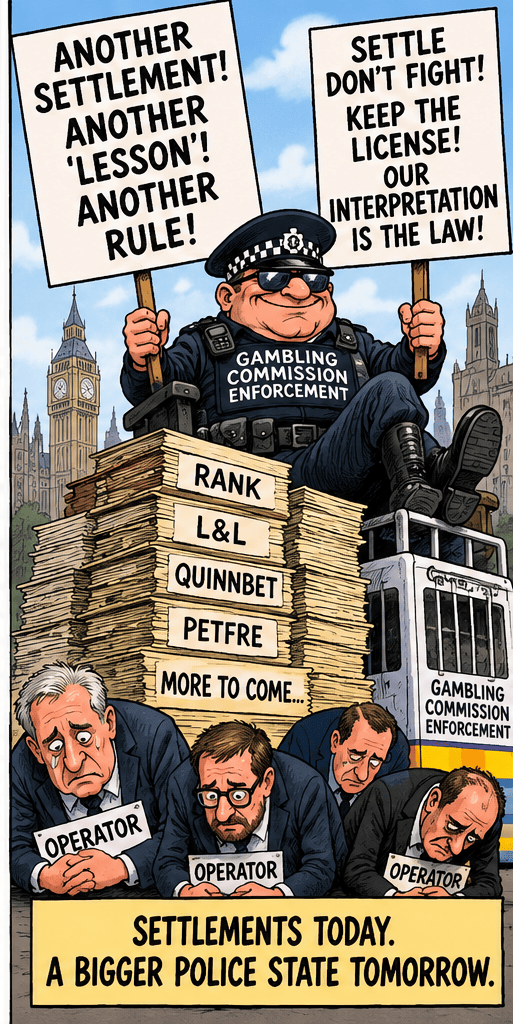
Rank, QuinnBet, Petfre, L&L and others have agreed substantial payments rather than fight the Commission’s interpretation through potentially lengthy and expensive proceedings.

I understand why, but it won’t be my direction of travel, these enforcement types deserve their day in front of a judge. In fact appeasement, driven by their lawyers, has been disastrous.

When a regulator controls the licence on which your business depends, today’s supine breed of industry lawyers advise you to settle rather than risk a contested enforcement action, a much larger penalty or even revocation.

For an individual company, that may be commercially sensible.

Each settlement, however, allows the Commission to publish another interpretation of the rules. The next operator is expected to have learned the lesson. Another settlement follows, and the interpretation gains further unmerited authority a judge would clearly reject.

Nobody has to prove that the Commission’s interpretation would survive a serious legal challenge.

The operators pay, their lawyers close the file, and enforcement moves on to its next target. Oh, and they love a good public razzing of the operators.

A habit has developed. The Commission investigates, the operator negotiates, the lawyers recommend settlement, and another public statement enlarges the expectations imposed on everyone else.

The operators have helped build the machinery now being used against them.

And their customers have had remarkably little say in any of it.

Is enforcement acting beyond its powers?

Licence condition 12.1.1 addresses anti-money-laundering controls. Social responsibility code 3.4.3 requires monitoring for indicators of harm and appropriate customer interaction.

Neither expressly imposes a general requirement to assess every customer’s gambling expenditure against income or wealth.

Yet enforcement statements increasingly appear to demand financial investigations beyond the Commission’s own description of its regulatory requirements.

That raises two separate issues.

First, whether enforcement is operating outside the Commission’s stated policy. On the evidence of these cases, there is a serious question for Sarah Gardner to answer. Before she departs to work for Harris Hagen of course

Second, whether particular enforcement expectations are ultra vires — beyond the Commission’s lawful authority.

That is ultimately a question of law, not simply opinion. Existing AML and customer interaction conditions confer significant powers, but they cannot be stretched indefinitely to impose obligations that have never been properly adopted.

A settlement doesn’t resolve that question. It is not a court judgment.

Nor does a succession of settlements turn an enforcement preference into legislation.

If the Commission wishes to require general assessments of customers’ financial capacity, it should identify the statutory authority, publish the requirement and subject it to the appropriate regulatory process.

It should not create a second rulebook through enforcement notices.

The danger is that enforcement has become accustomed to obtaining settlements and has started treating its own accumulated interpretations as though they carry the force of law.

It has become drunk on its own power. The perceived ‘success’of enforcement

That question deserves examination by Parliament, particularly if enforcement is operating beyond the boundaries of the Commission’s published policy.

Who protects my customers from the regulator?

The Gambling Act requires the Commission to aim to permit gambling insofar as reasonably consistent with the licensing objectives.

Parliament intended gambling to be lawful.

The Commission’s role is to protect vulnerable people, prevent crime and ensure gambling is fair. It is not to eliminate every possibility that an adult might lose money.

Those objectives do not give it an unlimited mandate to intrude into the private financial affairs of millions of customers.

Every unnecessary intervention makes licensed gambling less attractive.

Every intrusive request for bank statements encourages another customer to close an account.

Some will stop gambling. Others will find somewhere else to bet, including operators outside British regulation. Clearly I object to that..

The Commission acknowledges the danger of the illegal market. It should accept publicly its enforcement culture is contributing to that danger.

My customers deserve protection from fraud, dishonesty and genuinely irresponsible operators.

They also deserve protection from unnecessary regulatory intrusion. The right to say no to someone ringing them up, or worse, as with Big Corp, the suspension of their account if they refuse these measures

They have rights, privacy and the freedom to make their own decisions.So if a customer says he doesn’t want these interventions? He should, as he is with other forms of cold calling, be permitted to say no. To rely on his own recognisance

Those interests should carry considerably more weight than they appear to in the Commission’s enforcement statements.

 Gardner has some explaining to do

The Commission should be held to the same standards of evidence, proportionality and legal accountability that it demands of bookmakers.

Sarah Gardner should explain whether the Commission’s published position on affordability checks remains unchanged.

She should establish whether her enforcement department is applying that policy or imposing additional requirements through settlements.

She should explain whether voluntary operator procedures are being used to aggravate financial penalties.

And she should produce convincing evidence that the financial interventions being encouraged actually reduce gambling harm. Au minimas

The industry also needs to stop treating settlement as the automatic answer to every disagreement with the regulator. If nobody challenges questionable interpretations, they become the standards everyone is expected to follow.

I’ve spent decades building relationships with customers. I know that protecting them matters.

But protecting customers doesn’t mean taking away their judgment, disregarding their objections or treating their money as though it belongs to the state.

My customers are adults. They’re entitled to gamble. They’re entitled to privacy. And they’re entitled to expect the regulator to obey the limits of its own authority.

It’s time Parliament reminded the Gambling Commission of all three.

References: 40 years serving punters

And below? What they see as worthy
THE RIGHT TO BET

HOW THE GAMBLING COMMISSION IS FAILING PUNTERS AND RACING


Betting & Regulation

The Right to Bet:
How the Gambling Commission Is Failing Punters, Racing and the Law

Affordability checks are being imposed on millions of ordinary bettors on the basis of flawed evidence, without legal authority, and with consequences the regulator either cannot see or chooses to ignore. It is time to say so plainly.

Gambling is legal in Great Britain. It has been freely permitted, and indeed actively liberalised, since the Gambling Act 2005 created one of the most open betting markets in the world. The legislation that established this framework also created the Gambling Commission, and it imposed on that body a clear statutory duty: not merely to pursue the licensing objectives of protecting the vulnerable and preventing crime, but to permit gambling, in so far as the Commission thinks it reasonably consistent with those objectives.

That duty is not decorative. It is not a footnote. It sits in section 22 of the Act alongside the harm-prevention objectives, carrying equal legal weight. The Commission was never intended to be a body that restricts gambling whenever it can find a rationale — it was intended to be a regulator that allows a lawful activity to flourish while managing genuine risks. By any honest assessment, it has drifted very far from that mandate.

The “Choice” That Is No Choice at All

In a recent smartbetting podcast interview, Gambling Commission chief executive Andrew Rhodes was confronted with a direct and reasonable question. Punters are currently being told by bookmakers — among them bet365, one of the largest operators in the world — that if they wish to continue betting at certain levels, they must enrol in an open banking service called Bet Budget and grant access to their financial records. In some cases, we are told, this means sharing five years of complete bank account history across all accounts held.

The interviewer put this squarely to Rhodes: is this really a choice? Rhodes replied that it is a consumer choice — they decide whether or not to use open banking. The Commission is not doing this. The operator is doing this. And if you don’t like it, you can choose not to.

This answer deserves to be examined carefully, because it is not an honest account of what is happening.

The exchange — verbatim

“Their choice is adhere to this or you can’t bet with us — so it’s not really a choice, is it?”

— Interviewer, Smart Betting Club Podcast

“It’s a choice as in you can bet or you can’t.”

— Andrew Rhodes, Gambling Commission CEO

That response — “you can bet or you can’t” — is, in effect, an endorsement of coercion dressed up as consumer autonomy. The logic, applied consistently, would justify almost any operator imposition. A bookmaker could demand you provide your passport, your payslips, your mortgage documents and a letter from your employer, and the regulator’s position would be: that’s the operator’s commercial decision, and you are free not to use them. This is not consumer protection. It is the abandonment of it.

What makes it worse is that the Commission has spent years applying regulatory pressure — through enforcement reports, compliance activity, and implied threat of licence sanction — that has driven operators toward exactly this behaviour. The checks that Rhodes presents as “operator choices” are, in very large part, a direct consequence of Commission pressure applied through channels that were never subjected to formal rule-making or parliamentary scrutiny. Operators did not suddenly decide, of their own commercial volition, that demanding five years of bank records from punters was good for business. They did it because they were afraid of what would happen if they didn’t.

The Legal Duty Being Ignored

Section 22 of the Gambling Act requires the Commission to aim to permit gambling. This is not a vague aspiration. It is a positive obligation, and one that has meaningful content. The “reasonably consistent” qualifier that follows it requires the Commission to balance the duty to permit against the licensing objectives — it does not allow harm prevention to operate as an absolute trump card that extinguishes all other considerations.

Consider what proportionality requires in this context. The enforcement cases that provided the Commission’s original justification for pushing operators toward affordability checks involved genuinely extreme conduct: people losing hundreds of thousands of pounds without any check whatsoever, operators treating clearly distressed customers as VIPs. Nobody defends that. Nobody should.

But the regulatory response has not been calibrated to address those extreme cases. It has been applied at a level so far below them that it now routinely catches ordinary recreational punters — people losing a few hundred pounds a month on horse racing, betting within their means, causing harm to nobody — and subjects them to intrusive interrogation about their personal finances. The Commission’s own proposed thresholds would trigger checks at net losses as low as £150 in a month. At one point in the debate, the figure of £1.37 a day was cited as the effective threshold for frictionless financial vulnerability checks. The Commission did not dispute this arithmetic.

It is very difficult to argue that a policy causing documented, serious collateral harm — to a lawful industry, to hundreds of thousands of ordinary consumers, to the financial ecosystem of British horse racing — while failing to demonstrate any measurable reduction in problem gambling rates, satisfies the proportionality test that section 22 implicitly requires.

The “3%” That Tells a Misleading Story

Throughout this debate, the Commission and government have repeatedly invoked the figure that only 3% of accounts will be affected by enhanced financial risk checks. This has been treated as a reassurance — a signal that the vast majority of punters have nothing to worry about.

It is not an honest reassurance. It is a number that has been selected, presented and sustained in its most politically convenient form.

The 3.2% figure comes from a survey of 5.86 million active accounts covering May 2020 to April 2021. It represents the proportion of accounts losing £2,000 in a rolling 90-day period in a single year, at 2020 price levels. From that baseline, the problems compound quickly.

The thresholds were never inflation-adjusted before implementation. By summer 2024, when the policy was due to begin, £2,000 at 2020 prices had risen to approximately £2,528 in real terms. The figures simply weren’t updated. On inflation-adjusted terms, around 4.1% of accounts would breach the 90-day threshold, and 2.5% would hit the 24-hour £1,000 threshold. Because accounts can qualify for both, the true affected proportion is higher still — the Commission’s own analysis confirmed that between a fifth and a quarter of individuals identified by one threshold did not exceed the other, meaning the number of unique individuals affected is notably higher than either figure alone suggests.

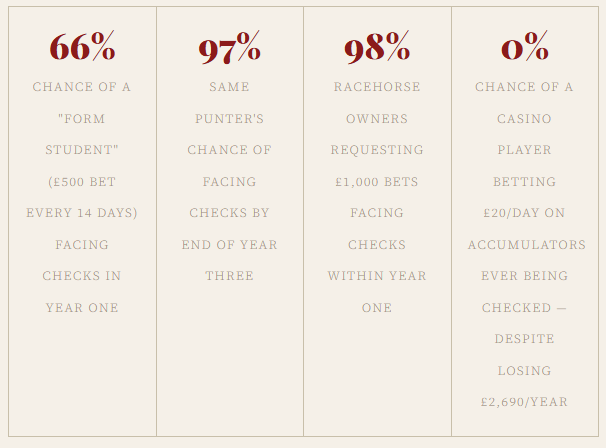
More importantly, 3% in year one is not 3% in year three. The process is not stationary. Accounts that avoid checks in year one can breach a threshold in subsequent years as results accumulate. Independent simulation modelling of typical racing punter profiles makes this vivid:

That last figure deserves emphasis. The threshold design is structurally biased. A punter placing modest daily accumulator bets at a high operator margin — losing nearly £2,700 a year — will never trigger a check, because steady daily losses don’t produce the variance spikes that trip the thresholds. Meanwhile a knowledgeable racing punter placing a single £500 fortnightly wager will almost certainly face checks within three years, even if they are profitable overall.

The policy, in short, disproportionately targets the most engaged, most informed, most economically valuable customers of horse racing — while largely ignoring the steady, high-frequency, low-unit gamblers that arguably represent a greater harm risk. This is not a technicality. It is a fundamental design failure that the Commission has never adequately addressed.

Horse Racing: Not Collateral Damage. A Foreseeable Catastrophe.

When the podcast interviewer asked whether the knock-on effect on sports like horse racing was “just collateral damage”, Rhodes demurred. He acknowledged racing’s unique dependency on gambling — 70% of its gross gambling yield comes from just 1% of accounts, five times the concentration of other sports. He acknowledged a declining consumer base. He then suggested that racing has structural problems independent of affordability checks and that it’s “not really for the Gambling Commission to comment on the economics of horse racing.”

This position is not sustainable. The Commission’s regulatory decisions are a direct, proximate, and now quantified cause of racing’s financial deterioration. The claim that this is somehow outside the Commission’s remit is precisely the kind of institutional detachment from consequences that makes this situation so frustrating.

“The Gambling Commission increasingly appears to be unaccountable and out of control. Moreover, they continue to be unable to demonstrate any evidence as to the impact that the current affordability measures are having on problem gambling rates.”— Martin Cruddace, CEO, Arena Racing Company

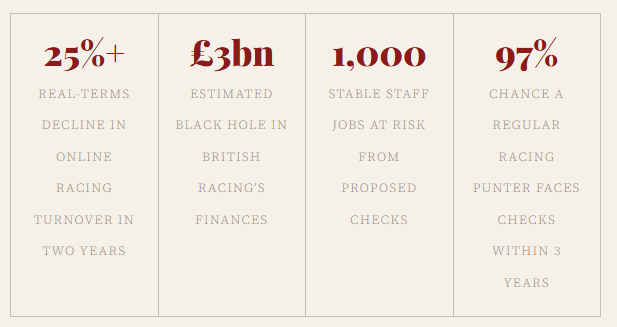
The numbers are not in dispute. Online racing turnover fell to £8.37 billion in the year to March 2024, compared to around £10 billion two years previously. Had it grown in line with inflation, it would be close to £11.5 billion — a real-terms decline of more than 25%, or a gap of some £3 billion. The BHA’s own data shows turnover year-to-date at end of August 2024 was down a further 9.5%, suggesting the decline is accelerating rather than stabilising.

The levy that funds racing’s prize money, its safety infrastructure, its veterinary research — all of it flows from betting turnover. British racing already receives less than 3% of betting revenue, compared to 7.7% in France and 8.4% in Ireland. It cannot absorb a 25% revenue shock. The mathematics are not complex.

Independent economic modelling by Regulus Partners, commissioned by the BHA, estimated that up to 1,000 stable staff jobs — one in seven — could be lost if the current proposals are implemented in full. These are not executive positions. They are the people who care for 14,000 thoroughbreds in training, who work in rural economies across Britain, who are not rich and who have no obvious alternative employment in the areas where racing yards operate.

“Racing cannot take any more financial setbacks. Racing and betting have come together on this issue like never before, because they know that they face the greatest ever threat to their existence.”— MP Philip Davies, Westminster Hall debate, February 2024

British racing contributes £4.1 billion to the British economy. It employs 80,000 people directly and 100,000 indirectly. It supports 8,000 small and medium enterprises. It touches 60 marginal parliamentary constituencies. It is not a fringe activity of the wealthy. It is a rural industry, deeply embedded in British cultural and economic life, and it is being hollowed out by a regulator that cannot demonstrate that what it is doing is working.

The Black Market: The Risk the Commission Keeps Minimising

Perhaps the most concerning aspect of the Commission’s posture throughout this period has been its persistent tendency to underweight the black market risk. At a Culture, Media and Sport select committee hearing, Rhodes said that every time he had heard someone say people were going to the black market, he had asked them where, and had never received an answer he could act on. This was presented as scepticism about the phenomenon’s scale.

Since then, Yield Sec data has shown a substantial increase in black market gambling, with visits to unregulated sites from UK users tripling during the 2022 World Cup, with peaks during Cheltenham and Royal Ascot — precisely the events most associated with the racing audience being disrupted by affordability checks. Rhodes contested the methodology. He may have points. But the direction of travel is not seriously in dispute, and his earlier scepticism now looks like something he has had to quietly retreat from.

What no one in the Commission’s leadership has grappled with honestly is the fundamental policy logic problem. If affordability checks in the regulated market drive even a fraction of consumers to the unregulated black market, the harm-prevention case for those checks collapses. Black market operators have no safer gambling tools, no self-exclusion obligations, no consumer protections whatsoever. They don’t want winning punters, and they are notorious for not paying out. A policy that displaces people from a regulated environment into that landscape has made those consumers worse off by every measure the Commission claims to care about.

The Commission appears to operate on an implicit assumption that bets which regulated operators are unable to take simply will not be placed. That assumption is not credible. It never was.

What Honest Accountability Looks Like

None of this is to argue that gambling requires no regulation, or that every punter is responsible and every operator trustworthy. The cases that prompted government action — people losing hundreds of thousands without any interaction from the operator — were genuinely indefensible. The regulatory impulse behind affordability checks is not unreasonable in origin.

But reasonable in origin does not mean appropriate in execution. And the Commission has failed, repeatedly and seriously, on execution:

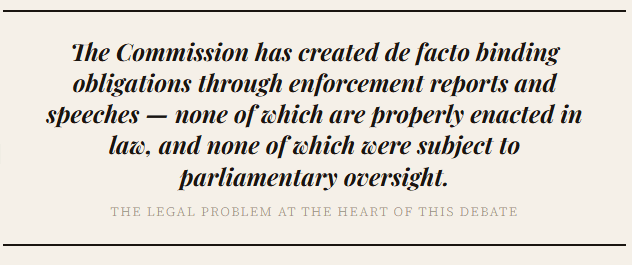
It applied regulatory pressure through enforcement reports and informal guidance without formal rule-making, creating binding practical obligations that were never subjected to legal scrutiny or parliamentary oversight. It allowed years of chaotic, inconsistent, operator-by-operator affordability checking to cause real harm to real consumers before attempting to standardise anything. It cited a “3% of accounts” figure that was stale, not inflation-adjusted, accounts-not-people, and systematically selected to understate real-world exposure. It pushed a pilot scheme to test whether frictionless checks work — after those checks had already been de facto implemented and had already caused the damage the pilot was supposedly designed to prevent. It has been unable, after years of this regime, to point to any evidence that problem gambling rates have fallen as a result. And it has watched a 25% real-terms collapse in horse racing turnover — a lawful industry it is legally obliged to permit — and described it as something it cannot properly comment on.

That is not the record of a regulator carrying out its statutory duty. It is the record of a body that has allowed one interpretation of one part of its mandate to crowd out everything else, without accountability and without evidence that the approach is working.

What Needs to Happen

The government should require the Gambling Commission to publish, before any formal implementation of enhanced financial risk checks, a full impact assessment that quantifies: the reduction in problem gambling rates attributable to current affordability measures; the proportion of consumers displaced to the unregulated market as a result; and the economic damage to horse racing and the wider rural economy. If such an assessment cannot be produced — because the evidence does not exist — then the policy cannot be justified.

The Commission should acknowledge formally, and in its regulatory guidance, that it has a statutory duty to permit gambling, and that this duty imposes a proportionality requirement on everything it does. The harm-prevention licensing objective does not override that duty. It must be balanced against it.

The open banking situation — where consumers are told by regulated operators that they must surrender five years of complete financial data or be refused service — must be directly addressed. Rhodes’ characterisation of this as a “consumer choice” is not acceptable from a regulator that is supposed to ensure gambling is fair and open. It is not open to say to a consumer: hand over your most sensitive personal financial information, or we won’t take your bet. That is not consumer autonomy. It is coercion, and the Commission should say so.

And the racing industry — which operates under a unique statutory funding relationship with the gambling sector through the levy — deserves specific recognition of the disproportionate impact that demand-side restrictions on betting turnover have on its finances. The Gambling Commission’s mandate to permit gambling is especially acute here: if it is permitting the regulated industry to collapse the consumer base for the very betting activity that funds an entire sport, it is not fulfilling its obligations under the Act.


Over 400 leading figures in racing — trainers, owners, jockeys, MPs of all parties — have signed an open letter to the Secretary of State calling for affordability checks to be scrapped. The BHA has warned that the Commission appears to be considering the pilot results without adequate government scrutiny of the consequences. Racing’s turnover is still falling.

The Gambling Commission was created to balance protection with permission. Right now, it is failing at both: it cannot demonstrate the protection is working, and it is presiding over the systematic destruction of a legal, economically vital industry it was legally obliged to protect. That is a regulatory failure of the first order, and it requires a direct political response — not more pilots, not more consultations, not more expressions of good intent.

British punters have a right to bet without being subjected to financial interrogation. British racing has a right to the regulatory environment the law promised it. Neither right is currently being honoured.

This analysis draws on the Gambling Act 2005, the Gambling Commission’s consultation responses and enforcement reports, parliamentary debate records (Hansard, February 2024), independent economic modelling by Regulus Partners, research published by the British Horseracing Authority, the Smart Betting Club podcast interview with Andrew Rhodes, legal commentary by Child & Child, and impact assessments published by gamblingreform.co.uk. All statistics are sourced from publicly available official data or named independent research.

Geoff Banks

CEO Geoff Banks Online

https://geoffbanks.bet

April 2026

the growth illusion

UK: industry stats – the growth illusion
 
In September 2019 we wrote a blog titled ‘the myth of growth’, using UK data to show that gambling had not grown materially in real terms for twenty years. A lot has changed in five years: online gambling has grown by another 30% and lockdowns have transformed the way people consume entertainment in a lasting way. However, fundamentally nothing has changed: people are spending less on licensed gambling in Great Britain now than they were in FY19. There are a number of important reasons for this which should shape domestic policy and international comparison as well as UK-facing operations management.


The Gambling Commission’s annual industry stats for FY24 (to March) look optically robust. The top five online group operators, for which the Commission publishes monthly revenue each quarter, have continued to lose share as expected, meaning underlying growth was higher. In the more consolidated betting market, top-five (really 4) share loss was 0.7ppts to 86.7%, which meant betting licensees outside the top operators grew by 10% YoY while the top operators grew by just 3%. The difference in gaming was even more pronounced, with 3.0ppts of share lost to 67.5%, meaning gaming operators outside the top five grew by 20% YoY, vs. 4%. While there are some operational reasons for this difference in performance (biggest isn’t always most innovative and at least two of the top five have suffered from self-inflicted problems caused by weak leadership), we continue to believe that the biggest reason for the shift is an uneven regulatory landscape. In our view, the £5 slots limit which is now been brought in will help to level the regulatory landscape down (something many of the top five advocated for on the basis their performance against the black market wasn’t being judged), thereby pushing a material volume of future underlying demand growth into the black market. Stronger-than-visible growth concentrated principally into the gaming long-tail is a double-edged message for future growth and channelling therefore.
 
UK online growth has accelerated into calendar 2024 (see Financial Update on Q3), in part because of comps but also because of a dangerously misunderstood phenomenon: the lag effect of money printing and inflation. It has been a while since a gambling operator tried to blame a ‘cost of living crisis’ on poor operational performance. The real reason for the 2022 economic shock (which had a negligible impact on gambling) was a hangover from frantic state money printing during lockdowns; these have now washed through, but average salaries in 2023 were 15% higher than in 2019 (note the gambling sector is not 15% bigger), broadly based salary increases are still coming through (c. +5%), while the government continues to use deficit spending to fund the public sector, adding to inflation risk going forward. When the economy was sclerotic, but inflation was consistently c. 2%, then 4% growth meant something; with inflation likely to remain volatile regardless of central bank predictions, absolute growth is far less relevant than relative growth. Largely due to wage increases and inflation, we expect high single digit growth for online gambling in the UK subject to black market leakage, but we expect a relative decline in gambling revenue – with landbased gambling bearing the brunt.
 
FY23-4 marked a period of optical landbased recovery, with all landbased sectors except the struggling National Lottery in growth. However, while landbased sectors in total added a net £63m to Britain’s gambling industry (excluding pub gaming machines, likely down), online added £471m, or 88% of all growth. This is a clear case of channel shift at work in ‘frog boiling’ form: landbased sectors are relieved to see some absolute growth but are losing relative market share. Again, inflation is an enemy in disguse – revenue goes up as businesses become less relevant and more fragile.
However, three long-term consumer demand trends are much more sticky than channel shift.
 
The first is that the National Lottery has failed to maintain early levels of consumer interests (note, now under new ownership). This has been compensated for in part by the strong rise of the Charity Lottery sector, but this is a complementary rather than competitive product: nothing can replace a well-run lottery in terms of mass market customer engagement.
 
Second, is the slow rise of slots content as the digital experience proved more flexible and increasingly more appealing than Britain’s stunted landbased offer. The new online stake restrictions are likely stymie and probably reverse this trend, in our view.
 
Third, is the consistency of betting: football has overtaken horseracing in absolute revenue (by only 15% in FY24 after a generation of predicted doom for racing from betting commentators who preferred opinion to evidence), but betting maintains remarkably consistent in terms of revenue mix over twenty-five years despite all the hype over growth. The relative growth in slots has therefore partially mitigated the relative decline of National Lottery revenue to keep gambling expenditure as a proportion of Household Disposable Income relatively stable at c. 1% over 25 years (note, FY9 was low because of the implementation of the Smoking Ban, the loss of S16/21 machines, and the onset of a global recession). However, an underlying decline can be detected and if the National Lottery is not turned around then it is likely to become more visible, in our view.For all the hype about a changing landscape, very little is changing in terms of underlying consumer behaviour other than channel shift. British consumers are, if anything, gambling less, albeit with revenue concentrated in a smaller number of participants.
 
The growth visible in the FY24 industry stats offers more to be concerned about than relief for a recently battered industry. For the British gambling industry to have a future that is not a story of increasingly pronounced relative decline temporarily disguised by inflation, it needs to achieve ‘just’ two things, in our view:
 ensure the legislative and regulatory framework keeps high value players in the licensed ecosystem; the opposite is currently being achieved (note, London has already largely lost a c. £150-300m annual high roller casino segment taxed at a marginal rate of 50% – sufficiently specialist to disappear largely un-noticed) create products that have genuine mass-market appeal (the Charity Lottery sector is the unsung standout success story here) 
These two drivers of industry sustainability sound simple, but they are proving dangerously elusive to deliver.
 
UK: RET policy – money, money, money: why the levy is far from funny
“What operators rightly hate being told is that they ought to be contributing more than they are to RG programs without being told what they are actually paying for. They then readily form the suspicion that most of their money is spent on the cost of employing an army of hostile public and quasi-public officials. These officials are then perceived as having as their primary concern not the alleviation of suffering but the retention or expansion of their own jobs. This in turn, can be suspected of leading to the proliferation of regulations that have little or no empirical basis.”
Professor Peter Collins, 2003
 
The decision to impoae a safer gambling levy on licensed gambling operators in Britian is by far the most ill-considered of the policies contained within the previous British Government’s white paper on regulatory reform. It is also likely to be the most significant in the longer term, with far-reaching consequences for the functioning of the gambling market, harm prevention and policy coherence.  In this article, we set out why we believe the levy is bad policy, what its outcomes are likely to be and how some of its worst consequences might be mitigated.
Why the levy is bad policy
The imposition of the ‘safer gambling’ levy has been dressed up by proponents as self-evident. After all, what could be more reasonable than requiring gambling businesses to fund the treatment of people suffering gambling disorder as well as work to better understand harm and to prevent its occurrence? The polluter, as the trope goes, should pay. 
 
The problem is that is not how our society works. In the normal world, businesses pay taxes at rates set by HM Treasury, which are used to fund public services, including healthcare, research and education. Charities, community groups, and private businesses address gaps in what the state is prepared to fund. The safer gambling levy breaks this model by requiring treatment and other costs to be funded directly from the expenditures of gambling consumers. In so doing, it sets a precedent for levies to be funded against general retail businesses (to recover costs from compulsive buying behaviour), internet providers (internet use disorder), coffee shops and teahouses (caffeine use disorder), pubs and bars (alcohol use disorder), and restaurants (obesity) among others. Followed to its logical conclusion, it proposes a healthcare system paid for by citizens according to their lifestyle choices. There is a dark and unsettling logic to this if applied consistently – but no obvious justification for its imposition on gambling consumers alone.
 
Combined with the draft guidelines of the National Institute for Health and Care Excellence, the levy will make treatment providers dependent upon the NHS through the stipulation that they may not seek funding or engage with gambling businesses – effectively penalising those organisations that support the current regulations. One consequence of this model is that – contrary to the spin – the levy increases the dependence of treatment and harm prevention providers on the industry (as a number of public health figures have already observed). In replacing a voluntary system of funding with a tax, the government will tie financing to industry revenues. If consumer spending with licensed operators reduces, so will funding. Organizations lobbying for tighter restrictions on gambling consumers (or higher taxes on operators) will do so in the knowledge that new measures may negatively impact their own finances. The Department for Culture, Media and Sport has forecast a net market contraction of 8.2% as a result of its white paper reforms but this is speculative, and the impact could well be greater (particularly if modernising reforms for landbased operators are delayed). There is a very good chance that the levy brings in less than expected, which would be a major problem if the levy was underpinned by an actual budget or assessment of need. 
 
The levy has been justified by reference to two factors: concerns over the perception of research independence under current arrangements (regardless of whether those perceptions are grounded in fact)the fact that some operators have contributed derisory amounts under the voluntary system 
The first suggests that government policy is now dictated by perception (which is in turn influenced by lobbying) rather than actual evidence. The second is a red herring – no gambling business of any scale has been guilty of under-funding; and the parsimony of the few is poor justification for the creation of a new tax, although it does justify targeted intervention.
 
The levy is also likely to be wasteful. HM Revenue and Customs already collects c. £3.5bn in specific gambling duties (in addition to general taxes less Output VAT) from the gambling industry, under direction from HM Treasury. The levy, however, envisages the establishment of an entirely new tax system, designed to collect roughly £100m under a non-fiscal authority, overseen by a levy board. While a Levy Board works well in racing, it is independently supervised with formal betting input (a board seat) and levy collected pays for clearly defined common interest objectives, neither of which apply to the safer gambling levy (although they could). Without these governance guard rails, the potential for waste, error and fraud is enormous, in our view.
 
The suggestion that the levy Is ‘smart’ appears to be Ir of those Orwellian conceits that has come into vogue in recent years (such as the idea recently expressed in the Lancet that state control is freedom). The logic for determining who pays what – including the exemption of the National Lottery – appears non-existent beyond the results of a sector and product popularity contest among the levy’s engineers. The application of a 1.1% rate to online gambling is justified by the idea that: i) it is associated with higher rates of ‘problem gambling’; and ii) remote operators have lower operating costs. The first is solely true of online gaming and is not true for betting – the ‘problem gambling’ rate for online sports bettors in the most recent Health Survey for England was just 1.2% (albeit it is dangerous to leap to causality given that PG rates are principally set by a product’s popularity). The second is true for some remote operators some of the time – but not for the many others: plenty of landbased businesses have higher margins than plenty of online businesses and the channel has little to do with the outcome. More generally, the suggestion that efficiency should be penalised hardly fits with the Government’s growth agenda. There is a reason why tax policy is generally set by finance ministries and not by regulators. Ironically, based on the premise that online gambling operators are able to pay more because of higher margins, they should be able to offset any margin-reducing tax increases with a reduced Levy rate, though we doubt the logic will be applied so robustly.
 
The levy is not so much smart as unfair. To provide one example, operators of gaming machines in bingo clubs and arcades are required to pay; but pubs and social clubs providing precisely the same machines are not. Further, the way that the Government has presented the tax is misleading because it is levied on suppliers (at 1.1%) as well as B2C operators (at between 0.1% and 1.1%). The effective rate of the new tax will therefore be applied inconsistently and at rates higher than claimed since we do not believe a recoverability mechanism (ie, the way VAT works outside the gambling sector) has been proposed – and it would make no sense if it did since gambling suppliers exist to serve gambling customers, who are being taxed through gambling operators. There is an additional irony that this highly complex levy, with multiple and arbitrary rates across different gambling products and channels, comes as the government simultaneously seeks to copy another of the previous government’s soundbite-driven schemes, since it will: consult next year on proposals to bring remote gambling (meaning gambling offered over the internet, telephone, TV and radio) into a single tax, rather than taxing it through a three-tax structure. This will aim to simplify, future-proof and close loopholes in the system. Perhaps someone needs to tune the governments’ wireless.
 
What can we expect next?
It has been claimed that the ‘safer gambling’ levy will result in greater resources and more certainty for harm prevention services, which would be a good thing. It will probably (depending on events) bring in more money than under the voluntary system; but that is not the same thing. For one thing, it will involve the creation of new administrative bureaucracy for which no published budget exists (a major lacuna) and, given the way that the state spends money, is unlikely to be either modest or well governed.
 
Half of the funds left over after as yet unknown administrative costs will be allocated to the perennially over-stretched National Health Service, which will almost certainly prioritise its own services over the requirements of the Third Sector. The charities, who have in some cases been effectively and diligently providing treatment to people with gambling disorder for more than half-a-century, will now be required to bid for the funds that were previously theirs. Several harm prevention organizations have already started to shut down programmes (including training for licensees) and making members of staff redundant (up to 150, if reports are correct). Made dependent on the state, treatment providers may find that they are required to fall in line with radical public health ideologies, such as the belief that adults bear no responsibility for their actions and harm is solely the result of exposure to ‘addictive products’. This denial of human agency breaches a core tenet of psychotherapy and has the potential to cause enormous damage to vulnerable people by institutionalising victimhood.
 
A further 30% of net funds will be allocated to the conveniently vague domain of ‘harm prevention’. Rumour suggests that the commissioner will be either GambleAware or OHID. The former has already called for mandatory health messages on all gambling advertisements (including for the National Lottery and horseracing); while the latter has manufactured suicide statistics and proposed ‘plain packaging’ (no colours, logos or images) for all gambling products. GambleAware may be slightly less illiberal than OHID, but both have trouble distinguishing between harmful gambling and gambling – a blind spot that ultimately leads to long-term prohibition via a medium-term funding bonanza. We can only imagine what they might get up to with up to c. £30m a year.
 
The final 20% is allocated to research under UK Research and Innovation (‘UKRI’). It is to be hoped that UKRI demonstrates greater scientific rigour and moral neutrality in commissioning research than the Gambling Commission, GambleAware, or OHID. The risk, however, is that it becomes a slush fund for anti-gambling activism that will be used not just in Britain but internationally to campaign for the prohibition of gambling once all the funding that can be extracted has been. In recent years, a profusion of clearly agenda-driven journal papers and reports of low academic quality have been published – often as a consequence of Gambling Commission or government funding – alongside a very small number of high-quality studies. There is a risk that the levy will be used to fuel a propaganda engine for an international anti-gambling movement. The reason why activists have prioritised the levy above all other matters is because they know just how large the prize is – up to £20m per annum.
 
For all the high-minded rhetoric, the levy seems destined to result in disruption to treatment services, increased stigmatisation of gambling as a legitimate adult pastime, and the production of misinformation on an industrial scale which politicians and bureaucrats seek to lack the discipline or inclination to critically assess. 
 
What should be done now?
The safer gambling levy may be bad policy, but it is now policy, and it will come into force next year. The question is therefore what ought to be done by licensees and others. We make three suggestions:
 Governance – there is a good chance that money raised by the levy will be used inefficiently, unscientifically and inappropriately. The process for how funds are allocated and assessed therefore requires close public attention. Scrutiny should be applied to the levy’s governance arrangements and the process of evaluation in 2030. Given what has gone before, it would be naive to trust those responsible to mark their own homework Continued support – a large number of harm prevention organisations now face uncertain futures. It would be a mistake, in our view, for operators to cease their support for charities and other harm prevention organizations once the levy kicks in even at the cost of ‘paying twice’. Several important programmes now face defunding (in addition to those that have already fallen by the wayside); and operators need insights from these groups in order to inform their own ‘safer gambling’ initiatives – for the sake of disordered gamblers and the sustainability of effective treatment, a distinction must be made between the sunk cost of a pollicised levy and productive expenditure on mitigating the harms that the licensed gambling sector does cause or exacerbate Critical analysis – the levy is likely to result in an expansion of anti-gambling activism, particularly in the domain of ‘research’, which will reach into other jurisdictions. To date, the licensed gambling industry in Britain and other jurisdictions has done an extremely poor job of assessing and (where appropriate) rebutting bad science. It is critical that it develops both the technical capability to scrutinise research and the willingness to call out misinformation (including misinformation which seems to support the industry). There is a good case to be made for building this capability on an internation basis.Ironically, the new levy is at least in part the unwitting handiwork of some of the largest licensees in Britain’s gambling industry whose lobbying made the policy almost inevitable. The Betting and Gaming Council’s endorsement of the policy was unfathomable to us at the time and continues to be so; it makes a lobbyist’s job much easier in the short-term but the industry’s job far harder in the long-term. There is a lesson here which the industry should now be able to perceive – policymaking is difficult in this space; and the pursuit of easy fixes is liable to end in disaster. Unfortunately, the government may have to wait a little longer before it arrives at this epiphany.  

Regulus partners
Disclaimer; The analysis provided in this report represents the opinions of the authors. Any assessment of trends and change is necessarily subjective. The information and opinions provided herein are not intended to provide legal, accounting, investment or policy advice, nor should they be used as a forecast. Regulus Partners may act, or have acted, for any of the companies and other stakeholders mentioned in this report.

Abusing NHS statistics

UK: ‘We don’t need no thought control’ – why the Gambling Commission should leave NHS stats alone

In recent years, the Gambling Commission has been on the receiving end of criticism from all sides of the so-called gambling debate. Last year, the MP, Sir Philip Davies declared that the regulator was “out of control”, while the Social Market Foundation has described it as “not fit for purpose”. The Commission has not publicly endorsed either of these views – or advertised them on its website – presumably because it considers them to be untrue as well as unflattering. Last month, however, the Betting and Gaming Council (‘BGC’) was asked by the Commission to make claims about the prevalence of gambling harms which are probably false – and to publish them on its website.


In an email recently released under the Freedom of Information Act, the Commission wrote:
 
“We’ve been keeping an eye on use of GSGB [Gambling Survey for Great Britain] data and use of figures as the official statistic. We’ve noticed that BGC still refers to previous stats, it’s not a misuse of stat issue but we’d be keen for you to start using the official figure moving forwards.”
 

This invitation was politely declined by the BGC on the grounds that it has greater confidence in NHS statistics (which are accredited by the UK Statistics Authority) than in the Commission’s (which are not). The BGC is similarly unlikely to profess that its members are (to borrow from Blackadder) ‘head over heels in love with Satan and all his little wizards’; but the Commission can always try.  

 
The regulator’s entreaties should be considered in the light of the following circumstances:
i) the balance of evidence indicates that the GSGB substantially overstates levels of gambling and gambling harm in Britain
ii) the Gambling Commission knows this
iii) in asking the BGC to go along with the charade, the Commission is acting, at best, inconsistently
iv) the GSGB is already being used (and misused) by activists, seeking to reopen the Government’s Gambling Act Review.


We examine each of these points in turn.  

 
1. The balance of evidence
The GSGB may be the new source of official statistics, but this does not mean it provides a reliable picture of gambling prevalence in Britain. To believe that it does, it is necessary to subscribe to the following:
        i.            Every single official statistic on gambling and harmful gambling produced over the last 17 years – by the National Health Service (‘NHS’), the Department for Culture, Media and Sport and the Gambling Commission itself – has been substantially wrong
      ii.            The NHS has serially misreported the prevalence of health disorders in general – and continues to do so
    iii.            Audited data on actual customer numbers using licensed operators is incorrect (or there is a massive black market that failed to show up in previous studies and of which the Commission was previously unaware)
     iv.            The opinion of the independent review (conducted by Professor Sturgis of the London School of Economics) that the GSGB may substantially overstate true levels of gambling and gambling harm is misguided
 

To believe that all these things are true (and to cajole others into professing the same) requires more than blind faith and a sheriff’s badge. Tellingly, the Gambling Commission does not have very much confidence in the GSGB itself; and has issued guidance that key results should be used “with some caution” or not at all.


2. Withholding evidence (again)
The Gambling Commission’s defence of the GSGB has largely consisted of attacks on NHS statistics, claiming that they have under-reported rates of ‘problem gambling’. While scrutiny is important, undermining accredited official statistics on health is a step not to be taken lightly. Some sort of evidence is required. For this, the Commission has relied upon a 2022 study which claimed social desirability response bias (ie, the fact that people sometimes answer survey questions in what they consider to be an acceptable rather than accurate fashion) caused under-reporting of ‘problem gambling’ in NHS surveys. This ‘evidence’ was thoroughly debunked by Professor Sturgis as part of his independent review – but for reasons known only to the Commission, the analysis was suppressed. It required a Freedom of Information Act request to secure the release of the information. This is not the first time that the Commission has prevented publication of critical evidence – having previously withheld survey data on customer opposition to affordability checks. Disclosures also reveal the Commission was warned by its lead adviser, Professor Heather Wardle, that social desirability response bias was likely to be a “marginal factor” in explaining differences between the GSGB and Health Surveys (and that the dominant factor of topic salience bias resulted in over-reporting in the GSGB). 
 
3. Two-tier thought policing?
In recent years, various parties have taken highly selective approaches to the use of ‘problem gambling’ statistics – often ignoring official estimates in favour of more convenient alternatives. Last year, the National Institute for Economic and Social Research did so in a report funded by a Gambling Commission settlement – using a rate two or three times higher than the official statistic. There is no suggestion that the Commission objected to this. In public consultations, the Commission itself relied on ‘problem gambling’ prevalence rates from the 2018 Health Survey for England rather than lower figures from the 2021 edition (ie, the official statistics at that time). In a speech in Rome last month, the chief executive of the Commission, Andrew Rhodes criticised those who wished to “turn the clock back” to previous official statistics, and in the very same speech cited participation estimates from ‘previous official statistics’.

 
4. The weaponisation of research
The importance of all of this has been amply demonstrated in recent weeks. Both the Institute for Public Policy Research and the Social Market Foundation cited the GSGB’s inflated rates of ‘problem gambling’ in support of demands for ruinous and self-defeating tax rates (as high as 66% of revenue); while GambleAware has used the survey findings to call for tobacco-style health warnings to be slapped on all betting and gaming adverts (including those for the National Lottery). The Commission appears, therefore, to be encouraging the use of inaccurate statistics on gambling harms in the knowledge that they will be used in support of an anti-gambling agenda.

Perhaps Sir Philip had a point after all…

REGULUS PARTNERS NOVEMBER 2024