My customers are not the Gambling Commission’s property
By Geoffrey Banks | 22 October 2026
I’ve been a bookmaker for decades despite not being that old. I’ve taken bets from people I’ve known for most of my working life. Some are wealthy, some aren’t. Some bet hundreds, others thousands. Most understand perfectly well what they’re doing. Gambling involves risk.
They’re my customers. Not the Gambling Commission’s.
They are adults spending their own money on a lawful pastime. They expect me to offer competitive odds, honour their bets, pay their winnings and treat them with honour.
They don’t expect to explain their salaries, savings, pensions or personal wealth to a stranger simply because they enjoy gambling. Or share it with my staff, quite understandably
And they certainly don’t expect a regulator to decide, years afterwards, whether I should have allowed them to bet.
Yet that is increasingly what the Gambling Commission’s enforcement department is doing.
The latest example is L&L Europe, which has agreed a substantial regulatory settlement following a Commission investigation. https://www.gamblingcommission.gov.uk/public-register/public-statement/detail/l-and-l-europe-limited-public-statement
There were genuine failings. Delayed withdrawals, inadequate responses to repeated failed deposits and breaches of agreed customer limits are matters a regulator should address.
But among the findings was criticism that L&L had not adequately established whether customer expenditure was proportionate to income or wealth.
There it is – affordability checks!
And although Andrew Rhodes has left the Gambling Commission to balls it up at Harris Hagen, the policies developed under his leadership have not simply disappeared with him. They’re doubling down on insane
Sarah Gardner is now Acting Chief Executive. The Commission remains responsible for explaining why its enforcement decisions demand financial assessments that its published policy says it doesn’t require.
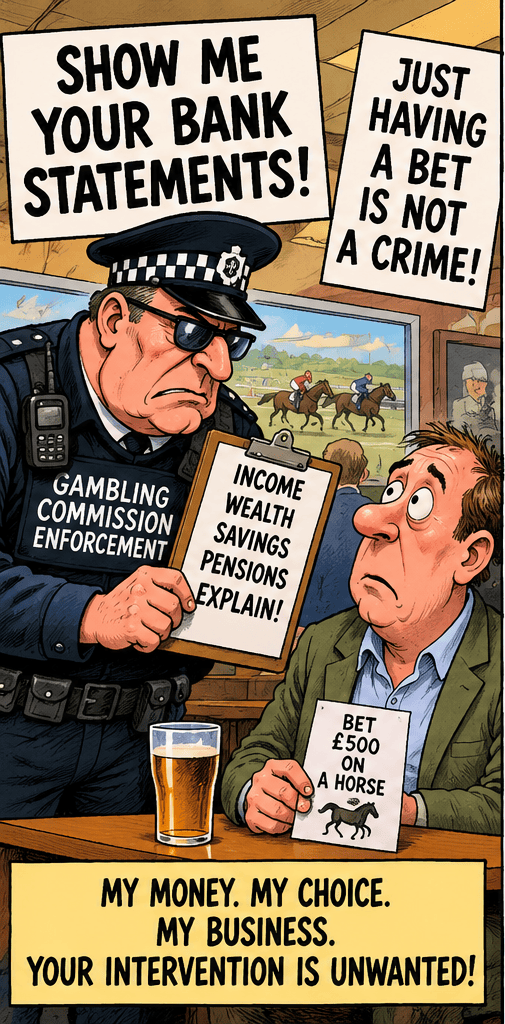
Customers don’t want financial interrogation to have a bet.
The Commission talks endlessly about protecting customers. It might consider listening to them before they all end up at Stake. Com
Many customers have made their objections to intrusive financial checks perfectly clear. They don’t want to hand over bank statements, payslips or access to their financial transactions to justify having a bet.
The Commission itself acknowledges that document checks are unpopular. Its financial risk assessment proposals are specifically intended to reduce reliance on them.
So why does its enforcement activity continue to encourage operators to investigate customers’ income and wealth?
I know customers who would sooner close an account than disclose their personal finances. I don’t blame them.
When did a bookmaker become entitled to examine someone’s bank statements simply because they want £500 on a horse?
And why should a successful businessman, who has spent decades accumulating his own wealth, have to prove to a gambling company that he’s allowed to enjoy it?
We don’t demand financial assessments before someone buys an expensive holiday, a luxury car or a painting.
Gambling carries risks, and those risks justify appropriate regulation. They do not justify treating every customer who spends substantial sums as financially incompetent.
The Commission increasingly forgets the difference.
Where is the evidence that these interventions work?
Here is the question Parliament should be asking.
Where is the convincing evidence that the financial interventions being imposed on customers actually reduce problem gambling?
Not evidence that some gamblers experience financial difficulties. We know that.
Not evidence that a credit-reference agency can identify missed payments or defaults. That is what credit-reference agencies do.
I mean evidence that requiring operators to interrupt betting, demand documents, investigate wealth and restrict customers produces a measurable reduction in gambling harm.
The Commission’s financial risk assessment pilot examined whether financial vulnerability could be identified and whether assessments could be conducted with minimal disruption.
That is not proof that the resulting interventions prevent problem gambling.
The Commission has decided to introduce financial risk assessments in stages and says it will continue evaluating their impact.
Yet operators are already being criticised through enforcement for failing to undertake financial enquiries that resemble the affordability assessments the Commission says it doesn’t require.
The burden should be on the regulator to demonstrate that its interventions are necessary, effective and proportionate. To prove these overbearing imposition on people are worthwhile
Instead, bookmakers face the financial consequences of failing to intervene, while the benefits of those interventions remain insufficiently demonstrated.
That is a remarkably one-sided arrangement.
Apparently, winning is now suspicious
Consider the recent Rank settlement involving Grosvenor Casinos.
The Commission criticised the absence of safer gambling interactions with a long-standing, wealthy customer who lost a substantial amount.
In another example, an established customer won around £260,000, subsequently lost £250,000 over 12 days and remained £10,000 ahead.
The Commission nevertheless criticised the absence of recorded safer gambling interactions.
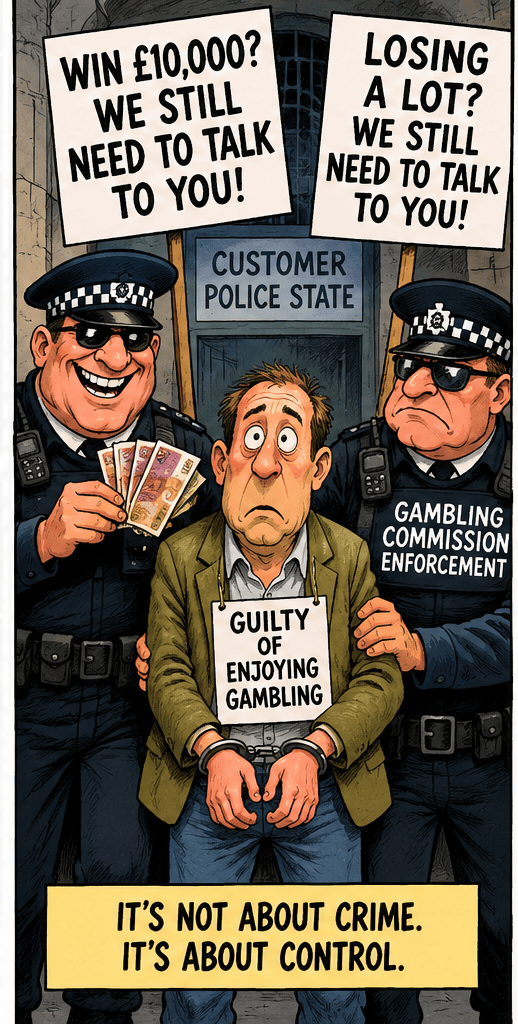
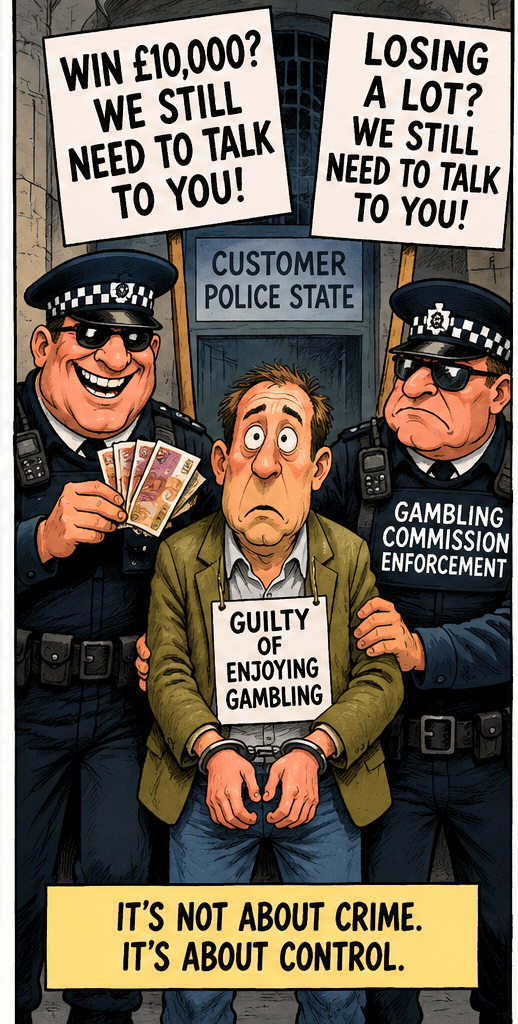
A customer wins £10,000 and the regulator finds fault with the operator.
A pattern of substantial gambling is not, by itself, proof that the customer has a gambling problem. Nor does a wealthy customer become financially vulnerable merely because the regulator considers the sums involved large.
What troubles me is the disappearance of proportion and context.
I know customers for whom a £5,000 bet is entirely ordinary. I know others for whom £100 is significant.
That is why personal knowledge and commercial judgment matter.
But the Commission’s approach encourages operators to disregard that knowledge and intervene defensively, because an ex copper in the enforcement department may take a different view two years later.
If a bookmaker intervenes unnecessarily, the customer suffers the inconvenience. If the bookmaker doesn’t intervene, the Commission may impose a substantial settlement.
The regulator faces neither consequence.
A policy the enforcement department appears to ignore
In May 2025 the Commission explicitly stated that it had no regulatory requirements for affordability checks and wasn’t proposing any.
Andrew Rhodes had previously explained to Parliament that affordability policy was being addressed through the Government’s Gambling Act Review White Paper process.
He has since departed. But his departure doesn’t repeal the Commission’s published policy.
Indeed, senior Commission officials subsequently made clear that the organisation intended to continue the regulatory approach established during his tenure.
Sarah Gardner therefore inherits a question that Rhodes never satisfactorily resolved.
The Commission distinguishes financial risk assessments from traditional affordability checks, saying they identify serious financial difficulties rather than calculate what a customer can afford.
Yet in the L&L case, enforcement criticised failures to assess whether expenditure was proportionate to wealth or income.
One customer deposited £4,400 within eight hours. The Commission questioned the provenance of the money, including the absence of evidence that it originated from employment, business income or savings.
Other warning signs justified AML enquiries. But money won from another bookmaker isn’t inherently suspicious, and customers aren’t obliged to finance their gambling from wages.
Checking whether funds are legitimate is one thing. Assessing whether a customer is sufficiently wealthy to gamble is another.
If the Commission’s policy says affordability checks aren’t required, why does its enforcement department appear to be demanding financial judgments that serve much the same purpose?
Sarah Gardner should explain whether enforcement is applying the Commission’s policy or developing its own.
When did an operator’s own policy become law?
L&L’s internal procedures said customer funds should ideally be evidenced as coming from employment or business income.
The Commission criticised the company for not following those procedures.
The LCCP requires effective AML controls, including proper implementation of relevant policies. But an operator’s voluntary precaution doesn’t automatically become an additional licence condition.
If a bookmaker introduces safeguards beyond the regulatory minimum, should it face greater punishment merely because it hasn’t followed every detail of them?
That creates a perverse incentive.
Write an ambitious compliance manual and hand the Commission more ammunition. Write the bare minimum and give it fewer opportunities to find fault.
The regulator should be encouraging operators to improve their procedures, not using voluntary commitments as an excuse to enlarge their regulatory obligations.If so, what should John Pierce and his merry band of stormtroopers in the enforcement unit fine themselves for departure from aim to permit, for example? Or application of affordability based enforcement? That’s a material breach. How many millions Mr Pierce should you pay?
If failures against those voluntary standards are increasing financial settlements, the Commission should explain how those penalties are calculated.
An operator shouldn’t be punished twice for the same underlying deficiency because it also happens to appear in its own manual.
The operators have helped create this mess
The industry cannot escape criticism either.
Major bookmakers began conducting their own affordability checks, often introducing restrictions and demands for financial information that went beyond what the Commission had expressly required. Unquestionably this was, in part l, driven by a desire to profile all clients and filter out traders
Instead of challenging the regulatory direction, parts of the industry effectively implemented it themselves.
Customers paid the price in intrusive questions, delayed transactions and closed accounts. They’ve departed gambling or opened up in Curaçao
Then came the settlements.
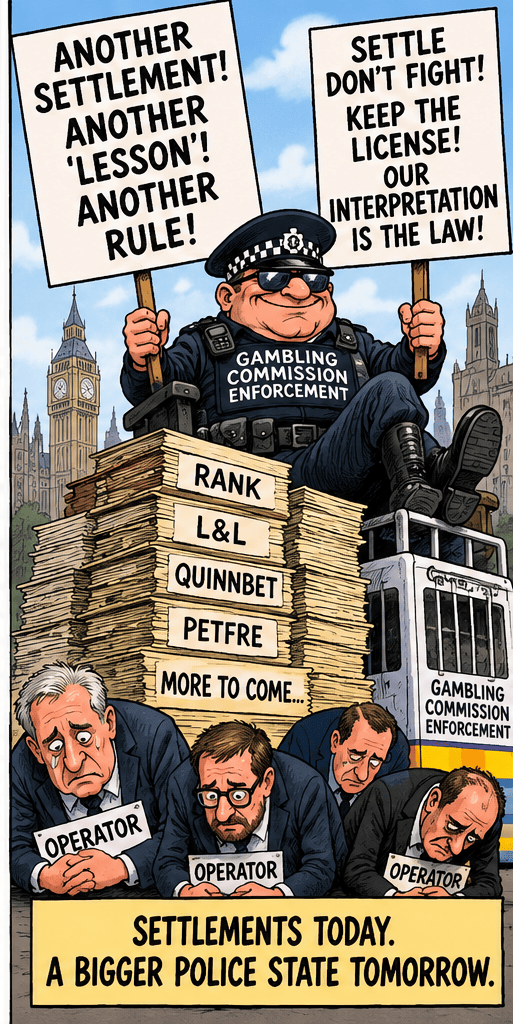
Rank, QuinnBet, Petfre, L&L and others have agreed substantial payments rather than fight the Commission’s interpretation through potentially lengthy and expensive proceedings.
I understand why, but it won’t be my direction of travel, these enforcement types deserve their day in front of a judge. In fact appeasement, driven by their lawyers, has been disastrous.
When a regulator controls the licence on which your business depends, today’s supine breed of industry lawyers advise you to settle rather than risk a contested enforcement action, a much larger penalty or even revocation.
For an individual company, that may be commercially sensible.
Each settlement, however, allows the Commission to publish another interpretation of the rules. The next operator is expected to have learned the lesson. Another settlement follows, and the interpretation gains further unmerited authority a judge would clearly reject.
Nobody has to prove that the Commission’s interpretation would survive a serious legal challenge.
The operators pay, their lawyers close the file, and enforcement moves on to its next target. Oh, and they love a good public razzing of the operators.
A habit has developed. The Commission investigates, the operator negotiates, the lawyers recommend settlement, and another public statement enlarges the expectations imposed on everyone else.
The operators have helped build the machinery now being used against them.
And their customers have had remarkably little say in any of it.
Is enforcement acting beyond its powers?
Licence condition 12.1.1 addresses anti-money-laundering controls. Social responsibility code 3.4.3 requires monitoring for indicators of harm and appropriate customer interaction.
Neither expressly imposes a general requirement to assess every customer’s gambling expenditure against income or wealth.
Yet enforcement statements increasingly appear to demand financial investigations beyond the Commission’s own description of its regulatory requirements.
That raises two separate issues.
First, whether enforcement is operating outside the Commission’s stated policy. On the evidence of these cases, there is a serious question for Sarah Gardner to answer. Before she departs to work for Harris Hagen of course
Second, whether particular enforcement expectations are ultra vires — beyond the Commission’s lawful authority.
That is ultimately a question of law, not simply opinion. Existing AML and customer interaction conditions confer significant powers, but they cannot be stretched indefinitely to impose obligations that have never been properly adopted.
A settlement doesn’t resolve that question. It is not a court judgment.
Nor does a succession of settlements turn an enforcement preference into legislation.
If the Commission wishes to require general assessments of customers’ financial capacity, it should identify the statutory authority, publish the requirement and subject it to the appropriate regulatory process.
It should not create a second rulebook through enforcement notices.
The danger is that enforcement has become accustomed to obtaining settlements and has started treating its own accumulated interpretations as though they carry the force of law.
It has become drunk on its own power. The perceived ‘success’of enforcement
That question deserves examination by Parliament, particularly if enforcement is operating beyond the boundaries of the Commission’s published policy.
Who protects my customers from the regulator?
The Gambling Act requires the Commission to aim to permit gambling insofar as reasonably consistent with the licensing objectives.
Parliament intended gambling to be lawful.
The Commission’s role is to protect vulnerable people, prevent crime and ensure gambling is fair. It is not to eliminate every possibility that an adult might lose money.
Those objectives do not give it an unlimited mandate to intrude into the private financial affairs of millions of customers.
Every unnecessary intervention makes licensed gambling less attractive.
Every intrusive request for bank statements encourages another customer to close an account.
Some will stop gambling. Others will find somewhere else to bet, including operators outside British regulation. Clearly I object to that..
The Commission acknowledges the danger of the illegal market. It should accept publicly its enforcement culture is contributing to that danger.
My customers deserve protection from fraud, dishonesty and genuinely irresponsible operators.
They also deserve protection from unnecessary regulatory intrusion. The right to say no to someone ringing them up, or worse, as with Big Corp, the suspension of their account if they refuse these measures
They have rights, privacy and the freedom to make their own decisions.So if a customer says he doesn’t want these interventions? He should, as he is with other forms of cold calling, be permitted to say no. To rely on his own recognisance
Those interests should carry considerably more weight than they appear to in the Commission’s enforcement statements.
Gardner has some explaining to do
The Commission should be held to the same standards of evidence, proportionality and legal accountability that it demands of bookmakers.
Sarah Gardner should explain whether the Commission’s published position on affordability checks remains unchanged.
She should establish whether her enforcement department is applying that policy or imposing additional requirements through settlements.
She should explain whether voluntary operator procedures are being used to aggravate financial penalties.
And she should produce convincing evidence that the financial interventions being encouraged actually reduce gambling harm. Au minimas
The industry also needs to stop treating settlement as the automatic answer to every disagreement with the regulator. If nobody challenges questionable interpretations, they become the standards everyone is expected to follow.
I’ve spent decades building relationships with customers. I know that protecting them matters.
But protecting customers doesn’t mean taking away their judgment, disregarding their objections or treating their money as though it belongs to the state.
My customers are adults. They’re entitled to gamble. They’re entitled to privacy. And they’re entitled to expect the regulator to obey the limits of its own authority.
It’s time Parliament reminded the Gambling Commission of all three.
References: 40 years serving punters
And below? What they see as worthy